Leading participants to and through retirement
We blend investment theory with decades of behavioral insights. Combined with a carefully calibrated balance between risk and reward, our TDF glide path is designed to help participants retire when they want, with enough money to fully support income throughout retirement.
Target Retirement series

The strategic asset allocation underpinning our portfolio construction
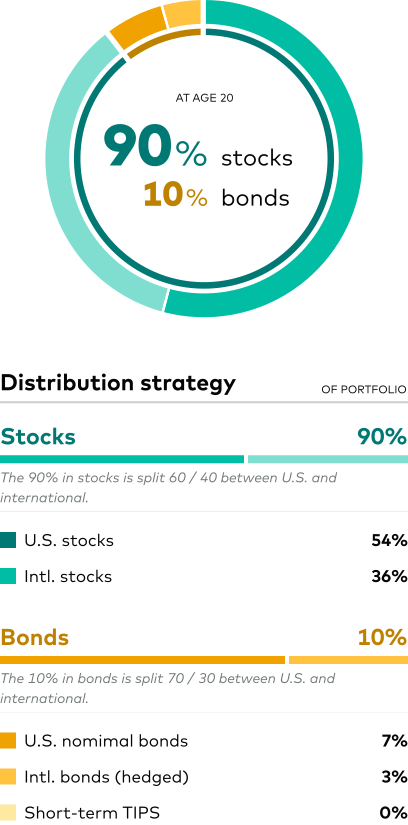
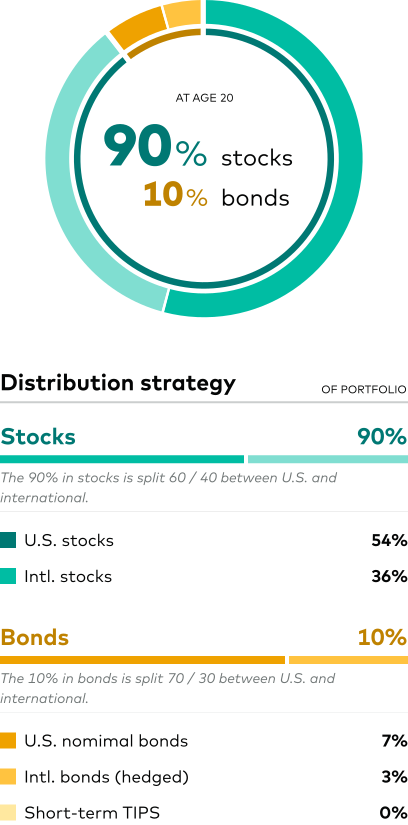
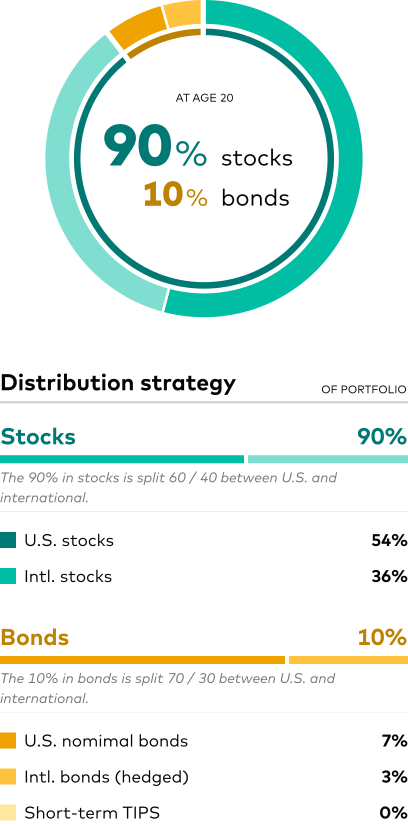
- Age 20
- Age 40
- Age 60
- Age 65
- Age 72
Age 20: Phase 1, early career


Age 40: Beginning of Phase 2, midcareer


Age 60: Phase 2, transition


Age 65: Phase 3, retirement and choice
Trust investors have the choice to remain on the default glide path or freeze their 50% stock allocation by converting to Vanguard Target Retirement Income and Growth Trust.


Age 72: Phase 4, withdrawal


Source
1 Craig Copeland, “EBRI IRA Database: IRA Balances, Contributions, Rollovers, Withdrawals, and Asset Allocation, 2017 Update,” EBRI Issue Brief, no. 513. Employee Benefit Research Institute, September 17, 2020.
Disclosures
For more information about Vanguard funds, visit vanguard.com to obtain a prospectus or, if available, a summary prospectus. Investment objectives, risks, charges, expenses, and other important information about a fund are contained in the prospectus; read and consider it carefully before investing.
All investing is subject to risk, including the possible loss of the money you invest. Diversification does not ensure a profit or protect against a loss.
Investments in Target Retirement Trusts and Funds are subject to the risks of their underlying funds. The year in the trust or fund name refers to the approximate year (the target date) when an investor in the trust or fund would retire and leave the workforce. The trust or fund will gradually shift its emphasis from more aggressive investments to more conservative ones based on its target date. The Income Trust/Fund and the Income and Growth Trust have fixed investment allocations and are designed for investors who are already retired. An investment in a Target Retirement Trust or Fund is not guaranteed at any time, including on or after the target date.
Vanguard is responsible only for selecting the underlying funds and periodically rebalancing the holdings of target-date investments. The asset allocations Vanguard has selected for the Target Retirement Funds are based on our investment experience and are geared to the average investor. Regularly check the asset mix of the option you choose to ensure it is appropriate for your current situation.
Investments in bonds are subject to interest rate, credit, and inflation risk.
Vanguard Target Retirement Trusts are not mutual funds. They are collective trusts available only to tax-qualified plans and their eligible participants. Investment objectives, risks, charges, expenses, and other important information should be considered carefully before investing. The collective trust mandates are managed by Vanguard Fiduciary Trust Company, a wholly owned subsidiary of The Vanguard Group, Inc.



U.S. bonds
We combine broad exposure to nominal U.S. investment-grade bonds with the safety and liquidity of government and short-duration bonds to provide diversification from the equity exposure.
Why do Vanguard Target Retirement strategies currently exclude high-yield bonds? They represent a small portion of the taxable U.S. bond market, and our research shows that overweighting them compared with the market has increased overall portfolio volatility and downside risk.

International bonds
Unlike most target-date funds (TDFs), we also include an allocation to international investment-grade bonds. This gives our TDF investors exposure to a greater number of 7,000+ securities, 40+ countries, yield curves, and economic and inflation environments. More importantly, the factors that drive international bond prices are relatively uncorrelated to those that drive U.S. bond prices. Our international fixed income assets are hedged to the U.S. dollar, which minimizes the volatility of global currency fluctuations.